

The Hidden Cost of Cancer: How to Get Help With Cancer Medical Bills


The Search for Help With Cancer Medical Bills After My Diagnosis
When I left the doctor’s office after learning that I had uterine leiomyosarcoma, I did not go directly home.
The cancer center had additional people available to help newly diagnosed patients. There were people and resources available to help with cancer medical bills, including financial assistance programs, hospital counselors, and support services who could guide patients. I soon learned that there
My doctor sent me to speak with one of them.
The woman gave me the standard brochures explaining the available programs. She told me about different kinds of assistance and signed me up for emails from the cancer center.
I was still trying to understand that I had a rare and aggressive cancer.
Now I was also being handed information about exercise programs, support services, financial help, and resources for cancer survivors.
I had not even begun treatment.
I still had large tumors inside my body.
I did not know whether I would survive.
Yet the first email I received was filled with activities for cancer survivors.
My immediate thought was:
“I am not a cancer survivor. I have cancer, and I do not even know how I am going to survive it.”
Then another thought came to me.
“That is going to be me someday.”
I did not feel like a survivor yet.
But somewhere inside me, I decided that I wanted to become one.
The Word “Survivor” Felt Too Early
People use the term cancer survivor in different ways.
Some organizations consider a person a survivor beginning on the day of diagnosis. Others use the word after treatment ends or after a person reaches a certain milestone.
At that moment, none of those definitions mattered to me.
I had just learned the name of my cancer.
I had not had surgery.
I had not started chemotherapy.
I did not know how far the disease had spread or how my body would respond to treatment.
Calling myself a survivor felt like saying I had completed a journey that I had barely begun.
At the same time, seeing programs created for survivors showed me that people did reach the other side of treatment.
The emails were not proof of what would happen to me.
They were proof that a life after cancer treatment existed.
I decided I wanted that life.
Then I Saw the Financial Assistance Information
Among the brochures and emails were descriptions of financial programs.
There were resources that might help with medical expenses, transportation, medications, food, lodging, and other needs.
That information caught my attention because I was still working and supporting myself.
I had health insurance.
Like many people, I might once have assumed that having insurance meant a serious illness would be financially manageable.
I quickly learned that insurance does not make cancer care free.
Over approximately a year and a half, my personal out-of-pocket cancer expenses exceeded "$30,000".
That was after insurance.
That amount did not include only one large hospital bill. Cancer expenses came from many directions.
There were appointments.
Scans.
Laboratory tests.
Surgery.
Pathology.
Chemotherapy.
Radiation.
Medications.
Specialists.
Copayments.
Deductibles.
Coinsurance.
Travel.
Parking.
Meals away from home.
Time away from work.
Costs that appeared small by themselves became enormous when added together.
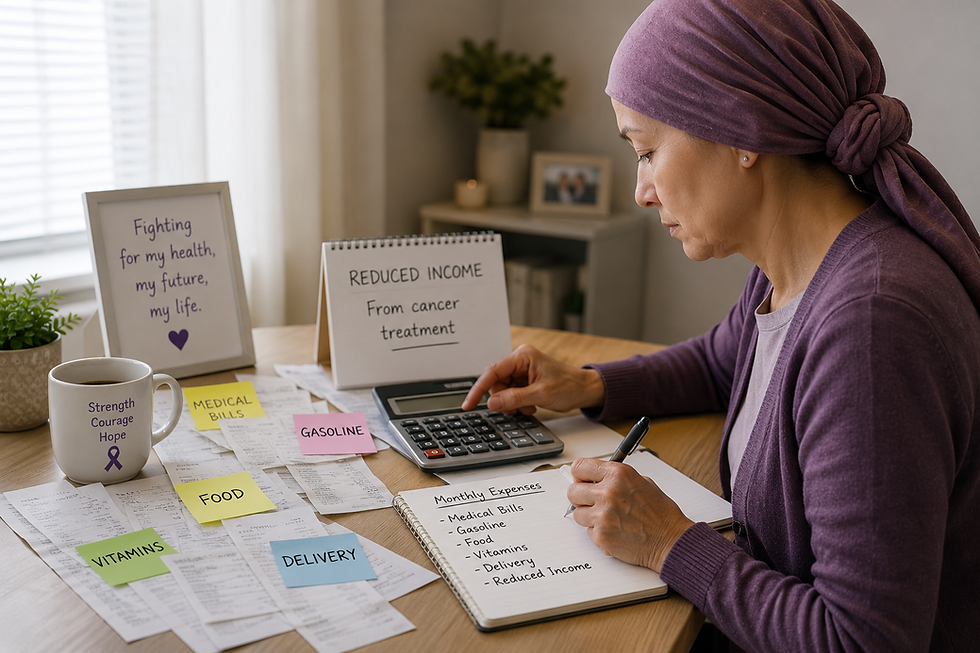
Cancer was threatening my life, but paying for cancer care was threatening the life I had built.
Nobody Tells You That You May Have to Pay to Stay Alive
When people talk about cancer survival, they usually talk about surgery, chemotherapy, radiation, medications, and follow-up scans.
They do not always talk about what happens when the bills arrive.
A person may be told:
“We have a treatment that could help you.”
What the patient may hear is:
“How much will it cost me to live?”
That is a terrible question to place on someone who is already afraid of dying.
I was a single mother.
I had to continue working because I could not afford to lose my income.
I had normal household bills before cancer entered my life. The mortgage or rent, utilities, groceries, transportation, insurance, and family needs did not disappear because I had tumors growing inside me.
Cancer added an entirely new category of expenses without removing any of the old ones.
The National Cancer Institute uses the term "financial toxicity" to describe the financial problems and stress caused by the cost of cancer care. It can include medical debt, loss of income, difficulty paying household expenses, and emotional distress related to money. People with cancer and cancer survivors experience financial hardship more often than people without cancer.
I did not know that term when I was diagnosed.
I only knew that I was scared.
The Financial Fear Began Before Treatment
The financial stress did not begin after the first large bill arrived.
It began as soon as I understood that I would need major treatment.
Before surgery, I was already wondering:
How much would my deductible be?
What percentage would insurance leave for me?
Would every doctor be in my network?
Would the anesthesiologist be covered?
How much work would I miss?
Would I still receive a full paycheck?
How would I pay the normal household bills?
What would chemotherapy cost?
What if treatment continued into another insurance year and the deductible started over?
What if I could not work?
What if I had to choose between treatment and keeping my home?
Those questions followed me into every appointment.
Cancer patients are often expected to concentrate on healing while also becoming experts in insurance policies, hospital billing, disability programs, medication assistance, and charitable grants.
That is too much for one frightened person to carry alone.
Health Insurance Did Not Protect Me From Financial Harm
I was insured, but I still accumulated more than $30,000 in out-of-pocket cancer expenses over about eighteen months.
The National Cancer Institute has reported that significant financial hardship can begin soon after an advanced cancer diagnosis and that having health insurance does not necessarily protect patients from financial problems.
Insurance policies contain deductibles, copayments, coinsurance, networks, prior authorization requirements, medication tiers, and annual out-of-pocket limits.
Even when the policy works as written, the patient may owe thousands of dollars.
The annual out-of-pocket maximum can also reset when a new plan year begins. A patient whose treatment crosses calendar or insurance years may face another deductible and another round of cost sharing.
The expenses outside the medical plan may be just as damaging.
Insurance usually does not pay your mortgage because chemotherapy made you miss work.
It does not necessarily replace all lost income.
It may not cover the gasoline, parking, hotel, food, childcare, home assistance, or accessibility changes required during treatment.
That is why the true cost of cancer is larger than the total printed on a hospital statement.
My First Rule: The Bill Is Not Final Until I Have Asked for Help
Over time, I developed a rule for cancer bills.
When a bill first arrives, I do not automatically treat the amount as the final amount I must pay.
I consider it unresolved until I have reviewed it and exhausted the available assistance.
That does not mean ignoring bills.
It does not mean refusing to pay legitimate charges.
It means asking questions before assuming that the first number is the last word.
Before paying a large medical bill, I believe patients should ask:
Was the claim processed correctly?
Did the provider bill the right insurance company?
Was the correct diagnosis or procedure code used?
Was any part of the claim denied?
Can the denial be appealed?
Is the provider in network?
Does the hospital offer financial assistance or financial advisors?
Is there a payment plan?
Can any fees be reduced?
Is there a medication assistance program?
Is there a cancer organization that helps with this type of expense?
Do I qualify for Medicaid, Social Security disability, VA care, or another public program?
Is there a patient navigator or financial counselor who can help?
Is there money available in the Health Savings Account or Flex Spending Account that I created with my job?
Nonprofit hospitals are required to maintain financial assistance policies for eligible patients who cannot afford their bills. Other healthcare facilities may also offer charity care, discounts, or payment arrangements. The Centers for Medicare and Medicaid Services advises patients to contact the facility’s billing department and ask directly about financial assistance.
Start With the Cancer Center’s Financial Navigator
One of the most valuable people in a cancer center may not be a doctor.
It may be the financial navigator, social worker, patient advocate, benefits counselor, or patient navigator.
The job title differs by facility, but these professionals may help patients:
Understand insurance coverage
Identify hospital financial assistance
Apply for medication programs
Find transportation or lodging support
Locate grants
Understand disability options
Communicate with billing offices
Organize insurance appeals
Connect with community organizations
The American Cancer Society recommends asking the cancer care team whether a financial counselor, social worker, or patient navigator is available and whether payment plans or local financial programs can help.
Research highlighted by the National Cancer Institute has also found that financial navigation can reduce patients’ financial burden by connecting them with insurance support, copay assistance, and other resources.
Do not wait until bills are already in collections to ask for this help.
Ask at the beginning.
Request the Hospital’s Financial Assistance Policy
Call the hospital billing office and use the exact words:
“I would like a copy of your financial assistance policy and application.”
Do not assume you earn too much.
Do not assume having insurance disqualifies you.
Do not assume assistance is only for people with no income.
Each hospital has its own rules. Some programs consider household income, family size, insurance coverage, total medical debt, and extraordinary circumstances.
A working person with insurance may still qualify for a partial reduction, an extended payment arrangement, or hardship consideration.
Ask:
What income limits apply?
Do you consider medical expenses in relation to income?
Does the program cover insured patients?
Which doctors and departments are included?
Does assistance apply to past bills?
What documents are required?
How long does approval last?
Must I apply again each year?
Will collection activity stop while my application is reviewed?
Keep a copy of every form and document you submit.
Review Every Explanation of Benefits
An Explanation of Benefits, commonly called an EOB, is not usually a bill.
It explains what the provider charged, what the insurance company allowed, what insurance paid, and what the patient may owe.
Compare the EOB with the bill.
Look for:
Services you did not receive
Duplicate charges
Incorrect dates
A provider listed as out of network
Claims marked denied
Missing insurance payments
Amounts that do not match
Procedures that may have required prior authorization
If something does not make sense, call both the insurer and the provider.
Write down:
The date
The time
The person’s name
The department
The reference number
What was discussed
What they promised to do
When you should follow up
Cancer brain, medication side effects, stress, and exhaustion can make it difficult to remember these conversations later.
Documentation matters.
Appeal Insurance Denials
Expect to have to do this. I have had to do this more times then I like to count. An insurance denial is not always the final answer.
Claims may be denied because of missing records, coding problems, authorization issues, medical necessity questions, filing errors, or network disputes.
Ask the insurance company for:
The exact reason for the denial
The provision in the policy supporting it
The appeal deadline
The documents needed
Whether the doctor can complete a peer-to-peer review
Whether an urgent appeal is available
The next level of appeal if the first one fails
Ask the doctor’s office to help.
Medical offices frequently have staff members who deal with prior authorizations and appeals. They may need to provide records or explain why the treatment was medically necessary.
Do not assume that a denial means treatment can never be covered.
Ask About the No Surprises Act
Federal protections may apply to certain unexpected out-of-network bills, including many emergency services and some non-emergency services received at an in-network hospital, hospital outpatient department, or ambulatory surgical center.
The No Surprises Act took effect on January 1, 2022. It generally protects people with many types of insurance from certain unexpected out-of-network charges, although the details depend on the service and coverage involved.
Patients who believe a bill violates these protections can seek help through the federal No Surprises Help Desk.
These protections were not available in the same form during the beginning of my own cancer journey, but current patients should know they exist.
Look Beyond the Hospital Bill
Cancer assistance may cover expenses other than direct treatment costs.
Programs may help with:
Transportation
Gasoline
Lodging
Meals
Childcare
Utility bills
Rent or mortgage emergencies
Prescription copayments
Insurance premiums
Medical equipment
Wigs
Compression garments
Home care
Counseling
The American Cancer Society maintains information about national, state, and local assistance and offers support programs that may include transportation and lodging depending on location and availability.
Some organizations help only with a particular cancer, treatment, medication, location, age group, or type of expense.
You may have to complete several applications.
That can be frustrating when you are sick. My most often said quote is, "I have more time then I have money,"
But a series of smaller grants can sometimes reduce a large financial burden.
Pharmaceutical Assistance May Reduce Medication Costs
Cancer medications can be extremely expensive. I had insurance, but the medication costs would meet my deductible in just 2 months' doses. How could I come up with that money for my work co-pays that fast? I called Pfizer, which had a program to help people meet their deductibles. Since I was using it for a rare cancer, it took a lot of calling between the specialty drug filler and Pfizer because of the coding. But I know this helped me.
Ask the oncology office or specialty pharmacy whether the drug manufacturer offers:
Copay assistance
Patient assistance for uninsured or underinsured patients
Temporary medication while insurance approval is pending
Foundation referrals
Case management
Insurance appeal support
Eligibility rules vary.
Some programs do not cover people enrolled in certain government insurance programs. Others are limited by income or available funding.
Funding may open and close throughout the year, so a program that has no money today may have assistance later.
Ask again.
Crowdfunding Is a Tool, Not a Failure
Some people use GoFundMe or another crowdfunding platform to help with cancer expenses.
There can be embarrassment attached to asking for money.
Many of us were raised to believe that we should handle our own obligations and never make our problems public.
Cancer can create expenses that few households could absorb without help.
Crowdfunding may help with medical bills, travel, household expenses, lost income, or support for children. The American Cancer Society has reported that cancer survivors increasingly use crowdfunding to help cover treatment and basic living expenses.
A campaign is not guaranteed to raise enough money.
It also requires honesty, privacy decisions, updates, and sometimes help from another person who can manage it.
When possible, ask a trusted relative or friend to organize the campaign so the patient does not have to carry one more responsibility.
My Experience With the VA
As I reviewed the available financial programs, I began thinking about my military service.
I had served in the United States Navy.
I thought the Department of Veterans Affairs might be able to help with my medical care.
When I went to the VA, I was told that because I was working and did not have a recognized service-connected condition, I did not qualify for the medical help I was seeking at that time. They said that because I had no service-connected condition recorded, had insurance, and a good-paying job, I didn't qualify for any medical or pharmacy help. They categorize medical priority and I was the lowest priority.
I was heartbroken.
Before treatment had even begun, I could see a huge financial burden coming toward me.
I had served my country, but I believed I had reached another closed door.
My experience happened under the rules and circumstances that applied to me at that time. VA eligibility can depend on service history, discharge status, disability status, income, priority group, special eligibility categories, and other factors. Current VA guidance says that most veterans who served on active duty and were not dishonorably discharged may qualify, although individual eligibility and costs vary. Having other health insurance does not automatically prevent someone from receiving VA health benefits.
Veterans should not rely only on an informal conversation or assume a previous denial still applies.
Apply formally.
Request the decision in writing.
Ask what evidence is needed.
Review eligibility again if income, disability status, law, or service-connected conditions change.
Service Connection and VA Disability Are Separate Questions
VA health care eligibility and VA disability compensation are related systems, but they are not exactly the same.
VA disability compensation generally requires evidence that an illness or injury was caused or worsened by military service. Eligible veterans may receive tax-free monthly compensation.
A cancer diagnosis may potentially be service-connected in certain circumstances, including some conditions related to recognized toxic exposures or other qualifying service.
That does not mean every veteran with cancer will qualify.
It means veterans should ask:
Could my cancer be related to an exposure during service?
Is my cancer on a presumptive condition list?
Do I need to file a disability claim?
Should I work with an accredited veterans service officer?
Can I appeal a denial?
Has the law changed since my previous application?
Am I eligible for VA health care even without disability compensation?
Do not pay an unaccredited person to file an initial VA claim without first learning about free accredited help.
Working While Going Through Cancer
I continued working because I needed income and insurance.
For many patients, stopping work is not a realistic option.
However, continuing to work during cancer treatment can create additional questions:
Am I eligible for job-protected leave?
Do I have paid sick time?
Does my employer offer short-term disability?
Can I work from home?
Can my schedule be changed around treatment?
Can I take intermittent leave?
Do I need workplace accommodations?
What happens to my insurance if I reduce my hours?
What if I become unable to work?
The answers depend on the employer, the employee’s work history, the type of insurance, state law, federal protections, and the medical situation.
Ask the human resources department for written information about:
Sick leave
Paid time off
Family and Medical Leave Act eligibility
Short-term disability
Long-term disability
Reasonable accommodations
Health insurance continuation
Employee assistance programs
Do not resign in a moment of panic without first understanding how the decision could affect income, insurance, disability benefits, and job protections.
Social Security Disability May Be an Option
Some people with cancer are unable to continue working.
Social Security Disability Insurance provides monthly payments to eligible people whose medical conditions significantly limit or prevent work and who have enough qualifying work history.
Approval is not automatic simply because someone has cancer.
The decision may depend on the cancer type, stage, treatment, expected duration, functional limitations, medical evidence, and work history.
Some serious conditions may receive faster processing.
A hospital social worker, disability attorney, benefits counselor, or Social Security representative may help explain the application process.
Build a Cancer Financial File
I recommend creating a separate financial section in your cancer organizer.
Include:
Insurance cards
Policy summaries
Deductible and out-of-pocket information
Explanation of Benefits statements
Medical bills
Payment receipts
Financial assistance applications
Approval and denial letters
Insurance appeal documents
Medication assistance information
Travel and parking receipts
Mileage records
Work leave documents
Disability applications
VA paperwork
Names and phone numbers of financial contacts
Notes from every billing conversation
Use folders, envelopes, a binder, or a secure digital system.
The system does not need to be beautiful.
It needs to help you find the right document when a billing office says it never received something.
Make a Master List Before Paying Bills
Create a simple table with these headings:

This helps prevent duplicate payments and shows which bills still need review.
Do not assume every bill from one surgery comes from the same organization.
The hospital, surgeon, anesthesiologist, radiologist, pathologist, and laboratory may bill separately.
Ask for an Itemized Bill
A summary bill may show only a total.
An itemized bill lists individual services, supplies, medications, procedures, and fees.
Request one when:
The amount seems unusually high
Insurance denied part of the bill
You do not recognize a charge
The dates appear wrong
You suspect duplicate billing
You need documentation for an assistance application
You are negotiating a balance
Compare it with your records and EOB.
You are allowed to ask what you are being charged for.
Do Not Put Medical Debt on a Credit Card Too Quickly
A credit card may seem like an easy way to make a hospital bill disappear.
But transferring medical debt to a high-interest card can remove options that might have been available through the hospital.
Before using a credit card, ask about:
Financial assistance
Interest-free payment plans
Reduced settlements
Hardship programs
Insurance appeals
Outside grants
Once the balance is placed on a regular credit card, it may be treated as ordinary consumer debt rather than a medical balance.
That can make the financial situation worse.
Accepting Help Is Part of Surviving
Cancer patients often say:
“Someone else needs the money more than I do.”
“I have a job, so I should handle it.”
“I do not want anyone to think I am begging.”
“I should have saved more.”
Cancer is not a moral failure.
Needing financial help during a medical crisis is not a character flaw.
Assistance programs exist because treatment costs can overwhelm hardworking people, including people with insurance and steady employment.
Accepting help may allow you to preserve money for housing, food, utilities, transportation, and your children.
It may also reduce enough stress for you to concentrate on treatment.
What Loved Ones Can Do
When someone says, “Tell me what you need,” the patient may not know.
Loved ones can offer specific financial and organizational help:
Sit with the patient while calling insurance
Create a spreadsheet of bills
Complete the nonmedical parts of assistance applications
Collect required documents
Organize a fundraiser
Set up a meal schedule
Drive to appointments
Track mileage
Research transportation programs
Review bills for duplicates
Help write appeal letters
Keep a calendar of deadlines
Contact organizations with the patient’s permission
Do not take over without asking.
Money is personal.
Let the patient decide what information may be shared and who may see it.
What I Wish Someone Had Told Me
I wish someone had told me that financial distress is a recognized side effect of cancer.
I wish someone had warned me that being insured would not protect me from enormous bills.
I wish someone had told me to meet with the financial counselor before treatment started.
I wish I had known to ask for financial assistance before paying every bill.
I wish someone had explained that an insurance denial could be appealed.
I wish someone had told me to keep every receipt, every EOB, every letter, and the name of every person I spoke with.
Most of all, I wish someone had said:
“Your first bill is not necessarily your final bill.”
I Had to Figure Out How to Pay to Live
After leaving the cancer center, I understood that I had two battles ahead.
I had to survive uterine leiomyosarcoma.
I also had to survive the cost of uterine leiomyosarcoma.
That is the part of cancer many people never see.
They see the hospital bracelet.
They see the chemotherapy chair.
They see the hair loss.
They see the surgery scar.
They do not see the patient sitting alone at the kitchen table with a stack of bills, wondering whether treatment will destroy everything they worked their entire life to build.
I was not asking whether I wanted to purchase something.
I was asking how I could pay for the care that might keep me alive.
It felt as though I had to pay to live.
A Practical Financial Checklist for Newly Diagnosed Patients
Before Treatment Begins
Ask for a financial navigator or oncology social worker.
Confirm that the hospital and doctors are in network.
Ask whether prior authorization is required.
Request a written estimate when possible.
Learn your deductible, coinsurance, and out-of-pocket maximum.
Ask which services may be billed separately.
Review leave, disability, and insurance benefits through work.
Ask about transportation and lodging support.
Apply for hospital financial assistance.
Research medication assistance before prescriptions are filled.
When Bills Begin Arriving
Match every bill to an EOB.
Request itemized statements.
Call about denied claims.
Appeal when appropriate.
Apply for charity care or hardship assistance.
Ask for an interest-free payment plan.
Keep detailed notes.
Do not ignore deadlines.
Avoid placing large bills on high-interest credit cards before exploring alternatives.
For Veterans
Apply formally for VA health care.
Request written eligibility decisions.
Ask whether the condition could be service connected.
Consult an accredited veterans service officer.
Review whether new laws or presumptions affect eligibility.
Appeal when evidence supports an appeal.
Hope for Today
When I first saw the cancer survivor emails, I thought they were meant for someone else.
I still had tumors inside my body.
I did not know whether I would live.
I did not know how I would pay for treatment.
But I saw that word:
"Survivor."
Part of me rejected it because I had not survived anything yet.
Another part of me claimed it as a destination.
Years later, I reached my five-year milestone.
The medical and financial road was not easy.
The bills were real.
The stress was real.
The fear of losing everything while fighting to stay alive was real.
But so was the help.
There were people to call, programs to explore, denials to question, applications to submit, and resources I did not know existed until I began looking.
Do not assume the first bill is the end of the conversation.
Do not assume you earn too much to ask.
Do not assume insurance processed everything correctly.
Do not assume a previous denial means you can never qualify.
You are fighting for your health.
You are also allowed to fight for the financial help that makes treatment possible.
Frequently Asked Questions
What is financial toxicity?
Financial toxicity is the financial distress or hardship caused by cancer and its treatment. It may include medical debt, lost income, difficulty paying ordinary expenses, and emotional stress about money.
Can insured cancer patients qualify for financial assistance?
Sometimes. Eligibility varies by hospital and program. Having insurance does not automatically mean a patient can afford deductibles, coinsurance, medications, or nonmedical costs. Ask each provider for its written assistance policy.
Are nonprofit hospitals required to offer financial assistance?
Nonprofit hospitals must maintain financial assistance policies for eligible patients. Patients should ask the billing department for the policy and application.
Should I pay a medical bill as soon as it arrives?
Pay valid bills by required deadlines when possible, but first compare the bill with the insurance EOB, review it for errors, ask about denials, and apply for assistance. Contact the provider rather than ignoring the bill.
Can I negotiate a medical bill?
Some providers may offer discounts, hardship reductions, or payment plans. Results vary, but patients can ask.
Does having private insurance disqualify a veteran from VA health care?
No. VA guidance states that other health insurance does not automatically prevent a veteran from receiving VA health benefits. Individual eligibility and costs depend on several factors.
Can a veteran appeal a VA denial?
Many VA decisions can be reviewed or appealed. Veterans may seek free assistance from an accredited veterans service officer and should keep copies of all decisions and medical evidence.
Is crowdfunding appropriate for cancer expenses?
It is a personal choice. Crowdfunding may help with medical and household costs, but patients should consider privacy, taxes, platform fees, effects on means-tested benefits, and who will manage the campaign.
Support on Your Journey
Cancer patients should not have to choose between protecting their health and protecting their families from financial ruin.
Surviving Life Lessons exists to help people learn from those who have already walked through difficult experiences.
A survivor may not be able to pay your bills.
But they may know which office to call, which question to ask, which denial to challenge, or which application helped them.
Sometimes that shared knowledge is the first step toward finding help.
Find Your Community
No one should have to face life's challenges alone. At Surviving Life Lessons, we believe in life survivors helping life strugglers. Explore our growing Community Groups to connect with others who understand your journey, share encouragement, and find hope through meaningful conversations. You'll also have the opportunity to introduce yourself and share your own story of overcoming. Your story matters. It may be the encouragement someone else needs to keep moving forward, reminding them that they are not alone and that hope is always possible.
Your Story Matters
We need your nice comments below! Your thoughts, experiences, and lessons learned might be exactly what someone else needs to hear today.
Drop a comment, Say Hello, and join the conversation.
Need More Personalized Support?
Everyone's journey is unique. If you're looking for personalized guidance, encouragement, or one-on-one support, explore our services to find the option that's right for you. We're here to help you take your next step with confidence and hope.
Helpful Resources for Your Journey
Explore our collection of books, journals, coloring books, and printable PDFs designed to encourage, inspire, and support you every step of the way.
References
National Cancer Institute. “Financial Toxicity and Cancer Treatment.”
National Cancer Institute. “Financial Navigators Reduce the Cost of Cancer Care.”
American Cancer Society. “Managing the Cost of Cancer Care.”
American Cancer Society. “Cancer Financial Assistance and Resources.”
Centers for Medicare and Medicaid Services. “Apply for Medical Bill Financial Assistance.”
Centers for Medicare and Medicaid Services. “Medical Bill Rights.”
Department of Veterans Affairs. “Eligibility for VA Health Care.”
Department of Veterans Affairs. “Eligibility for VA Disability Benefits.”
Social Security Administration. “Disability.”
About the Author:
Deborah Ann Martin is the founder of Surviving Life Lessons, a published author, poet, speaker, and trainer with over 20 years of management experience across multiple industries. An MBA graduate, U.S. veteran, single mother, and rare cancer survivor, Deborah brings both professional expertise and lived experience to her writing on resilience, leadership, personal growth, and overcoming adversity. Her mission is to empower others with practical wisdom and real-life insight to navigate life’s challenges with strength and purpose.


Comments