

The Financial Cost of Cancer Treatment: What Surviving Cancer Really Cost Me

The Financial Cost of Cancer Treatment: The Medical Bills Were Only the Beginning
The financial cost of cancer treatment was at least $27,000 in insurance out-of-pocket expenses during the first part of my journey.
That amount came from three separate insurance years.
From August through December 2020, I reached my $9,000 out-of-pocket maximum.
In 2021, I reached another $9,000 maximum.
Then, in 2022, I reached another $9,000 out-of-pocket maximum within approximately the first two months of the year.
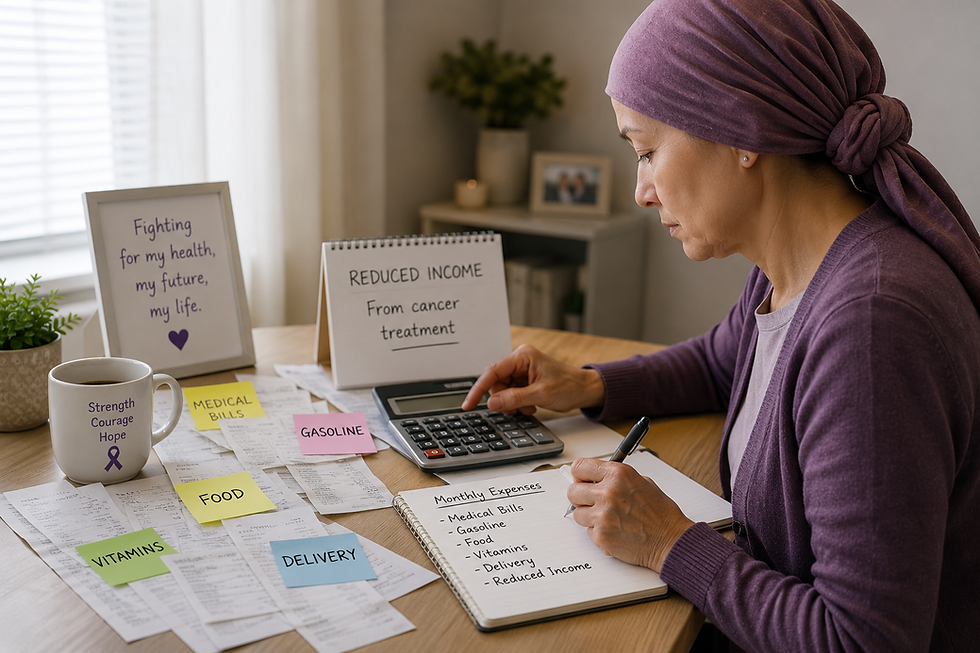
That was $27,000 before counting gasoline, food changes, vitamins, delivery fees, tips, reduced income, or the time my children missed from work to help me.
When people talk about the cost of cancer, they often think about surgery, chemotherapy, radiation, prescriptions, and hospital bills.
Those costs are enormous.
They are still only part of the financial story.
I Had Health Insurance
I was not uninsured.
I had employer-sponsored health coverage.
I had an income.
I had a Health Savings Account.
I understood insurance better than many people because I had experience handling business, technology, and administrative systems.
None of that protected me from the financial burden of cancer.
The National Cancer Institute uses the term **financial toxicity** to describe the financial problems and stress that can come from cancer care. It may include deductibles, copayments, prescription costs, lost income, transportation, and the effects of being unable to work normally. Financial hardship can affect insured patients as well as those without insurance.
Insurance prevented the bills from becoming even larger.
It did not make cancer affordable.
Five Months Cost Me $9,000
My Stage IV uterine leiomyosarcoma diagnosis was confirmed in September 2020.
From August through the end of December, my medical care included imaging, biopsies, major surgery, tumor testing, back surgery, port placement, emergency care, chemotherapy, wound complications, bloodwork, and many specialist appointments.
In that short period, I reached the $9,000 out-of-pocket maximum under my insurance plan.
That represented only about five months.
Then January arrived.
The insurance calendar restarted.
My body did not restart.
Cancer Does Not Care When the Deductible Resets
Cancer treatment does not pause on December 31.
My chemotherapy continued into January 2021.
I still needed doctors, laboratory testing, imaging, medication, and follow-up care.
But the insurance calculations began again.
A new calendar year meant another deductible and another out-of-pocket maximum.
I had just reached the point where covered care cost me less, and then I was returned to the beginning of the financial cycle.
That is one of the cruelest parts of a serious illness that crosses insurance years.
The disease is continuous.
The financial protection is temporary.
Another $9,000 in 2021
I reached another $9,000 out-of-pocket maximum in 2021.
Chemotherapy had ended, but medical care did not.
After doxorubicin, I needed continuing heart evaluation because that chemotherapy can affect cardiac health.
My care included:
Cardiology appointments
EKGs
An echocardiogram
A stress test
Cardiac catheterization
Laboratory monitoring
Follow-up cancer care
Imaging
Prescription medicines
Hormone maintenance treatment
Evaluation and management of side effects
Before I began letrozole, my doctors also ordered a bone-density test to establish a baseline.
That was medically appropriate because aromatase inhibitors can affect bone health.
It was also another test, another appointment, and another bill.
Treatment Ends Before the Bills Do
People may assume that the expensive phase ends when chemotherapy ends.
My experience was different.
Chemotherapy created the need for additional medical care.
The cancer treatment affected my heart risk.
Hormone treatment created the need to watch my bones.
Side effects required more appointments.
Laboratory changes required monitoring.
The end of one treatment did not close the account.
It opened additional categories of care.
By Early 2022, I Had Reached Another Maximum
In 2022, I reached the $9,000 out-of-pocket maximum within approximately two months.
That meant I had personally paid about $27,000 in covered medical expenses across parts of three insurance years.
This number does not represent the total amount billed by the hospitals, doctors, laboratories, pharmacies, imaging centers, or other healthcare services.
It represents the amount I was responsible for under my insurance structure before the plan provided the maximum level of covered financial protection available to me.
It also does not include everything that insurance refused to recognize as a medical expense.
The Official Bills Were the Easy Costs to See
Insurance claims produce paperwork.
There are statements.
There are explanations of benefits.
There are patient balances.
There are receipts.
Those costs can be tracked.
The harder costs are the ones that slowly drain the household without arriving in an envelope marked "cancer treatment".
They include:
Gasoline
Vehicle wear
Parking
Food while traveling
Delivery charges
Tips
Vitamins
Supplements
Changed grocery purchases
Lost wages
Reduced disability pay
Time away from work
Time family members miss from work
Additional household help
Recovery time
The loss of rest
The National Cancer Institute recognizes that cancer’s financial burden may include transportation, lodging, lost work, reduced productivity, and money spent by informal caregivers as they assist the patient.
My Cancer Center Was More Than an Hour Away
My cancer center was approximately one hour and ten minutes from my home.
That was one direction.
A round trip required more than two hours of driving before accounting for traffic, parking, waiting, treatment, laboratory work, or appointments.
At the beginning of treatment, I was traveling there at least three or four days each week.
That was a tremendous amount of gasoline.
It was also a tremendous amount of time.
Transportation Was Part of the Treatment
The cancer center could have the best surgeons, oncologists, radiation professionals, nurses, laboratories, and equipment in the world.
I still had to reach it.
Every appointment required:
Preparing to leave
Driving more than an hour
Paying for gasoline
Possibly paying for food
Finding parking
Walking into the facility
Waiting
Receiving care
Driving home
Recovering afterward
Transportation problems can cause patients to delay or miss cancer care. National Cancer Institute information recognizes that transportation is a major social and financial need for people receiving treatment.
I was fortunate that I could reach my appointments.
Reaching them was not free.
Three or Four Days a Week Adds Up Quickly
One round trip might seem manageable.
Three or four round trips every week create a different reality.
The gasoline cost repeats.
The vehicle mileage increases.
Oil changes and maintenance arrive sooner.
Tires wear.
The person driving loses hours that could have been used for work, rest, household care, or family.
Even when no hotel is required, distance places a financial burden on treatment.
The medical claim may show the cost of chemotherapy.
It does not show what it cost to get the patient into the chair.
My Children Lost Work Time Too
Cancer did not only take time from me.
My children took time away from their jobs to help.
They transported me.
They attended important appointments.
They assisted around surgeries and treatment.
They helped when I could not safely manage everything alone.
Their lost work time may not appear on my insurance documents.
It was still part of what cancer cost our family.
Caregiving often requires relatives to miss work, reduce hours, pay for food or travel, and provide unpaid logistical support.
A family can lose money even when the patient’s medical bill is fully covered.
Surgery Reduced My Income
When I had surgery, I used short-term disability.
My benefit replaced approximately 60 percent of my normal pay.
That support was valuable.
Without it, I might have received no income while I recovered.
But losing 40 percent of a paycheck during the same period when medical expenses are at their highest creates another financial problem.
The mortgage, utilities, groceries, insurance premiums, and ordinary household bills do not fall by 40 percent because the patient is healing.
Cancer increases expenses while often reducing income.
That combination creates pressure quickly.
Short-Term Disability Was Not Full Financial Protection
Short-term disability helped me remain financially afloat.
It did not make me financially whole.
I was recovering from major surgery while trying to manage:
A reduced paycheck
A new cancer diagnosis
Insurance balances
Transportation costs
Household expenses
Treatment planning
Family responsibilities
The word "disability benefit" may sound as though the problem has been solved.
A partial-income benefit is not the same as receiving full wages.
It is a bridge.
Sometimes it is a narrow one.
I Worked During Chemotherapy
During chemotherapy, I continued working.
My employer provided accommodations that allowed me to flex my hours around treatment and appointments.
I could make up work during evenings or weekends.
That helped protect my income and employment.
It also meant there was very little time left for recovery.
Flexibility Did Not Create More Hours
Flexible work can be a blessing.
It can also hide how much a sick employee is carrying.
If I spent several hours traveling to treatment, receiving chemotherapy, completing bloodwork, or attending a medical appointment, those hours did not disappear from the workweek.
I made them up.
I worked weekends.
I adjusted my schedule.
I kept meeting responsibilities.
The accommodation helped me remain employed.
It did not give my body more energy.
The Hidden Cost Was Rest
Rest does not produce a receipt.
Losing it still has consequences.
When I worked around chemotherapy appointments, the time that might have allowed my body to recover became work time.
I was earning my paycheck by using weekends and flexible hours.
That protected my finances in one way.
It increased the physical burden in another.
Cancer patients often face impossible choices:
Protect income or protect energy
Attend the appointment or meet the deadline
Rest or make up the hours
Take leave or lose part of the paycheck
Ask family for help or allow them to protect their own jobs
Not every cost is measured in dollars.
Food Became More Expensive
My diet changed after cancer.
Before diagnosis, I bought the foods that fit my ordinary life, preferences, family, and budget.
During and after treatment, food became part of supporting a body dealing with surgery, chemotherapy, anemia, deficiencies, diabetes, chronic illness, and medication effects.
I began purchasing foods based more heavily on:
Protein
Iron
Vitamins and minerals
Lower carbohydrate needs
Blood-sugar control
Tolerance during chemotherapy
Foods I could manage when taste changed
Ingredients that supported my medical plan
The grocery bill changed.
“Eat Healthy” Has a Price
People casually tell cancer patients to eat healthier.
Healthy food is not always cheap.
Fresh produce spoils.
Lean proteins can cost more.
Specialized foods for diabetes or digestive tolerance may cost more.
Small convenient foods that a nauseated person can tolerate may cost more per serving.
A patient may also waste food because something that tasted acceptable yesterday becomes unbearable after the next chemotherapy treatment.
Food insecurity, nutrition, and cancer care are closely connected, and the cost of treatment can force patients to reduce grocery spending at the same time they are being told that nutrition matters.
Cancer-Surviving Food Was Not a Cure
I want to be careful with the phrase "cancer-surviving foods".
I changed my diet to support my body through cancer and treatment.
I did not believe food could cure Stage IV uterine leiomyosarcoma.
No special food, diet, vitamin, mineral, or supplement has been proven to cure cancer or guarantee that it will not return. Supplements can also interact with cancer medicines, so they should be reviewed with the medical and pharmacy teams.
The food changes were supportive care.
They were not a replacement for surgery, chemotherapy, radiation, or maintenance treatment.
Chemotherapy Left Me Deficient
Chemotherapy and surgery affected my appetite, blood counts, and nutritional needs.
Food tasted terrible.
Some days, eating felt like work.
My laboratory testing showed areas that needed attention.
I began using food and medically reviewed supplements to replace nutrients my body was lacking.
That added another regular expense.
A Multivitamin Was Not Enough for Everything
A general multivitamin did not always contain the strength or combination needed for the deficiencies my doctors were monitoring.
I began purchasing separate vitamins and minerals.
Depending on my medical plan and laboratory results, those included support for issues such as:
Iron
Vitamin D
Calcium
Magnesium
B vitamins
Other identified needs
The exact supplements and doses belong to my personal medical plan.
Another patient should not copy my supplement routine without medical and pharmacy guidance.
The important financial point is that every additional bottle costs money.
Pill Bottles Multiply Quietly
A bottle may cost $8, $15, $25, or more.
One bottle may not seem financially significant compared with chemotherapy.
Several bottles purchased month after month become another household expense.
Then there are organizers, glucose supplies, over-the-counter treatments, supportive products, and replacements.
Insurance may cover some prescriptions.
It often does not cover ordinary vitamins and supplements.
The body may need them because of treatment, while the patient pays for them as if they were optional personal purchases.
COVID Changed How I Bought Everything
My treatment began during the COVID-19 pandemic.
I was receiving chemotherapy and had a weakened immune system.
Avoiding unnecessary exposure mattered.
I paid to have groceries and other supplies delivered.
Delivery was a blessing.
It allowed me to receive food, medicine, and household necessities without walking through crowded stores during a dangerous period.
It was not free.
Every Delivery Included More Than the Product
The order included:
Delivery fees
Service charges
Possible price differences
Tips
Minimum-order requirements
Occasional substitutions
Items that were unavailable
The cost of convenience
I was grateful for the workers who brought what I needed.
I believed they deserved tips.
That meant each order cost more than shopping in person.
Safety Had a Price
People sometimes describe delivery as a luxury.
During chemotherapy and COVID, it was part of protecting my health.
I was trying to reduce exposure while my immune system was vulnerable.
I could not always go to the store safely.
I also did not always have the strength.
Delivery helped me survive treatment at home.
The extra charges were the price of access and risk reduction.
Gratitude Does Not Erase the Cost
I can be grateful for delivery and still acknowledge the expense.
I can be grateful for short-term disability and still acknowledge the 40 percent income loss.
I can be grateful for insurance and still acknowledge paying $27,000.
I can be grateful for flexible work and still acknowledge losing rest.
I can be grateful for my children’s help and still recognize that they lost work time.
Gratitude and financial strain can exist together.
The Cancer Bill Spread Across the Household
Cancer affected how money was used throughout my home.
Money that might have gone toward:
Savings
Retirement
Home repairs
Family activities
Travel
Debt reduction
Emergency funds
Ordinary enjoyment
went toward staying alive and managing treatment.
Even when I could pay the bill, I lost what that money might have built elsewhere.
That is part of financial toxicity too.
The Cost Did Not End With NED
Reaching no evidence of disease did not end the expenses.
I still needed:
Cancer surveillance
PET scans and other imaging
Laboratory testing
Signatera testing
Port care
Cardiology
EKGs
Echocardiograms
Stress testing when ordered
Bone-density testing
Diabetes care
Eye examinations
Foot examinations
Prescriptions
Pain-management care
Massage therapy
Other specialists
Some costs changed.
They did not disappear.
Cancer Created Chronic Healthcare Costs
Doxorubicin added heart-monitoring needs.
Exemestane added bone and musculoskeletal concerns.
Lorlatinib added diabetes, cholesterol, neuropathy, and other monitoring needs.
Mobility problems added orthopedic care and knee injections.
Diabetes added eye and foot care.
Survivorship became a long-term healthcare system.
The financial story therefore cannot be limited to the first chemotherapy year.
The Cost of Cancer Includes Becoming a Chronic Illness Patient
A patient may finish chemotherapy and continue paying for:
Late effects
Long-term side effects
Maintenance medicine
Specialist monitoring
Rehabilitation
Chronic pain
Diabetes
Heart problems
Bone health
Mental health
Mobility aids
Home accommodations
The cancer may be NED while the financial effects remain active.
Tracking the Money Matters
Cancer produces too much paperwork to manage through memory alone.
Helpful records may include:
Insurance explanations of benefits
Medical bills
Receipts
Prescription costs
Mileage
Parking expenses
Lodging
Meal costs during treatment travel
Delivery fees
Disability payments
Missed work
HSA withdrawals
Manufacturer-assistance information
Payment-plan agreements
Charity or grant applications
The National Cancer Institute encourages patients to keep medical and financial information organized and to ask billing departments, social workers, and financial-navigation programs for help.
Ask Before Paying the Bill
Patients may be able to ask about:
Prompt-payment discounts
Payment plans
Financial assistance
Charity care
Manufacturer assistance
Transportation help
Medication grants
Copay programs
Social-worker support
Financial navigators
Corrected billing codes
Insurance appeals
Not every program applies to every person.
Asking can still matter.
Later in my journey, obtaining an expensive off-label cancer medicine required working with insurance, the manufacturer, the VA, the pharmacy, and coding systems.
Financial advocacy became another form of medical advocacy.
Insurance Knowledge Became a Survival Skill
I learned to know:
My deductible
My out-of-pocket maximum
When the plan year restarted
Which facilities were in network
Which pharmacies were covered
Whether authorization was required
How prescription assistance worked
Which expenses counted toward the maximum
Who needed to submit additional documentation
When a billing code was wrong
Patients should not need advanced administrative knowledge to receive cancer care.
In reality, understanding the system can determine whether treatment is affordable.
Caregivers Need Financial Information Too
My children and especially my caregiving son needed clear information.
A caregiver may need to know:
Which bill is due
Which insurance number to call
Which prescription needs assistance
Where receipts are stored
Whether leave paperwork was submitted
Which appointments require transportation
What costs may be reimbursed
Who can speak for the patient if she is too sick
This is another reason I created tools to help patients and families organize the cancer journey.
Confusion costs money.
Questions to Ask About Cancer Costs
What is my deductible?
What is my annual out-of-pocket maximum?
When does the insurance year reset?
Is this doctor or facility in network?
Does this test need prior authorization?
What will the treatment probably cost me?
Is there a less expensive medically appropriate location?
Is manufacturer assistance available?
Does the cancer center have a financial navigator?
Are payment plans available?
Is there help with transportation?
Can appointments be combined?
Does my employer offer short-term disability?
How much income will disability replace?
Can I use flexible scheduling or intermittent leave?
Which expenses should I document?
Questions to Ask About Food and Supplements
Is a supplement medically necessary?
Did laboratory testing show a deficiency?
Could this vitamin interact with cancer treatment?
Is a lower-cost equivalent available?
Can the nutrient be obtained safely through food?
Will insurance cover a prescription-strength version?
Can a dietitian help me plan affordable meals?
Do my diabetes, kidney, thyroid, or cancer medicines change what is safe?
Are there food-support programs available?
Questions to Ask About Work
What leave benefits do I have?
How much income will short-term disability replace?
How long can the benefit continue?
Can I work a flexible schedule?
Can I use intermittent leave?
What accommodations would help?
Who completes the medical forms?
How will health-insurance premiums be paid while I am out?
What happens if I cannot return on schedule?
How will reduced hours affect retirement or other benefits?
Employment and disability rules vary. Patients may need human-resources, benefits, legal, union, or financial advice.
What I Wish Someone Had Told Me
I wish someone had told me that having insurance would not protect me from tens of thousands of dollars in personal expenses.
I wish I had known that the out-of-pocket maximum could reset while treatment continued.
I wish someone had told me to calculate the cost of gasoline and travel before choosing a cancer center.
I wish I had understood how much income short-term disability would replace before surgery.
I wish someone had warned me that flexible work could protect my paycheck while taking away much of my recovery time.
I wish I had known how expensive nutrition changes, supplements, delivery fees, and tips could become.
I wish more people understood that the cost of cancer continues after chemotherapy.
Most of all, I wish someone had said:
“Keep track of the hidden costs too. The medical bills are only the part of cancer that comes with an invoice.”
Hope for Today
I paid approximately $9,000 from August through December 2020.
I paid another $9,000 in 2021.
I reached another $9,000 maximum within the first two months of 2022.
That was at least $27,000 in insurance out-of-pocket expenses.
Then there was the gasoline for a cancer center more than an hour away.
There were three or four trips each week during the busiest period.
There was the work time my children lost.
There was the 40 percent of my pay that short-term disability did not replace.
There were weekends spent making up work instead of resting.
There were new foods.
There were separate vitamin bottles.
There were grocery deliveries, service charges, and tips.
There was the financial cost of trying to remain safe during COVID while chemotherapy weakened my immune system.
I was fortunate in many ways.
I had insurance.
I had employment.
I had an HSA.
I had family support.
I had delivery services.
I had doctors.
I had access to treatment.
Fortune did not make the cost small.
Cancer affected my health, time, work, food, transportation, family, and future savings.
That is why financial conversations should begin early.
Patients deserve to know not only what treatment may do to the body, but what it may do to the household.
Frequently Asked Questions
What is financial toxicity?
Financial toxicity is the financial distress and hardship caused by the cost of cancer care. It may include medical bills, prescription expenses, reduced income, transportation, and other treatment-related costs.
Did health insurance cover my cancer?
Insurance paid a large portion of the overall medical cost, but I still owed approximately $27,000 across parts of three insurance years.
What was my annual out-of-pocket maximum?
My maximum was approximately $9,000 during the years discussed in this article.
Did the cost restart every January?
My insurance plan operated on a calendar year, so the deductible and cost-sharing cycle restarted when the new year began.
Did chemotherapy create additional expenses after treatment?
Yes. I later needed cardiac monitoring, bone-density testing, maintenance treatment, laboratory work, and care for long-term effects.
Why did food cost more?
I changed what I purchased to support nutrition, blood counts, diabetes management, treatment tolerance, and deficiencies. Specialty or higher-quality foods can cost more.
Can vitamins interfere with cancer medicine?
Yes. Some vitamins, supplements, herbs, and foods may change how cancer medicines work. Patients should review them with oncology and pharmacy professionals.
Was delivery a luxury?
For me, delivery reduced exposure during COVID while I was receiving chemotherapy and helped when I lacked the strength to shop. It was useful but added fees and tips.
Did working during chemotherapy save money?
It helped protect my income, but flexing hours and working weekends reduced the time available for rest and recovery.
Can financial navigators help?
Some cancer centers offer financial navigation to help patients understand bills, insurance, assistance programs, and other resources. Results vary, but asking for support may reduce costs and confusion.
Support on Your Journey
Cancer financial stress can continue long after the first surgery or chemotherapy treatment.
Surviving Life Lessons Community Groups are being formed so patients, survivors, and caregivers can discuss medical bills, insurance, work, transportation, food costs, prescriptions, disability leave, and the hidden expenses of staying alive.
You should not have to carry the financial side of cancer silently.
Find Your Community
No one should have to face life's challenges alone. At Surviving Life Lessons, we believe in life survivors helping life strugglers. Explore our growing Community Groups to connect with others who understand your journey, share encouragement, and find hope through meaningful conversations. You'll also have the opportunity to introduce yourself and share your own story of overcoming. Your story matters. It may be the encouragement someone else needs to keep moving forward, reminding them that they are not alone and that hope is always possible.
Your Story Matters
We need your nice comments below! Your thoughts, experiences, and lessons learned might be exactly what someone else needs to hear today.
Drop a comment, Say Hello, and join the conversation.
Need More Personalized Support?
Everyone's journey is unique. If you're looking for personalized guidance, encouragement, or one-on-one support, explore our services to find the option that's right for you. We're here to help you take your next step with confidence and hope.
Helpful Resources for Your Journey
Explore our collection of books, journals, coloring books, and printable PDFs designed to encourage, inspire, and support you every step of the way.
References
National Cancer Institute. “Financial Toxicity and Cancer Treatment.”
National Cancer Institute. “Managing Cancer Costs and Medical Information.”
National Cancer Institute. “Advanced Cancer Causes Money Problems, Even for the Insured.”
National Cancer Institute. “Financial Navigators Reduce the Cost of Cancer Care.”
National Cancer Institute. “Addressing the Social Needs of People With Cancer.”
National Cancer Institute. “Diets, Supplements, and Cancer.”
National Cancer Institute. “Cancer Therapy Interactions With Foods and Dietary Supplements.”
Centers for Medicare & Medicaid Services. “Health Insurance Terms You Should Know.”
About the Author:
Deborah Ann Martin is the founder of Surviving Life Lessons, a published author, poet, speaker, and trainer with over 20 years of management experience across multiple industries. An MBA graduate, U.S. veteran, single mother, and rare cancer survivor, Deborah brings both professional expertise and lived experience to her writing on resilience, leadership, personal growth, and overcoming adversity. Her mission is to empower others with practical wisdom and real-life insight to navigate life’s challenges with strength and purpose.


Comments